
If you ask an HR leader to name the most critical challenges facing employee benefits today, rising costs are probably at the top of the list. Soaring healthcare premiums have been pressuring benefits budgets, and they’re expected to worsen, with a record 9% cost increase expected next year. Some employers have started shifting costs or even cutting benefits. According to a recent Mercer survey, 38% of CFOs support raising employee contributions to relieve operating cost pressures.
Inflation is also affecting workers’ ability to engage with benefits. With more of their take-home pay going toward rising prices, they have a harder time paying healthcare premiums and contributing to 401(k)s. Worse, many workers use 401(k) loans and hardship withdrawals to cover emergency expenses because they lack savings. And so it’s no surprise that saving is now the number-one employee financial priority, even more than retirement and investing.
So the question benefit leaders are asking is: How do you support employee savings without pressuring budgets? Here, Chime Workplace breaks down why employee savings matters, which workforce segments struggle to save, and how leaders are responding.
Why Employee Savings Is the Most Important Financial Wellness KPI
A Vanguard study shows that the most significant factor in financial health is establishing a minimum savings level. Saving $2,000 creates a bigger financial boost, on average, than doubling income. The reason? Workers without savings experience high levels of stress and constantly worry about running out of money.
When they start saving, they are no longer preoccupied with today’s bills and can confidently invest in their future. They are more than twice as likely to contribute to a retirement account. And their likelihood of taking a 401(k) loan drops by half.
They focus four more hours per week at work; greater focus brings greater productivity. Their turnover rate drops by 28%, and employee satisfaction rises by 10%. Plus, lower financial stress reduces absenteeism and tardiness by 25%.
So saving is clearly good for employee financial health, commitment, and productivity. The problem? Too many workers have trouble starting. About two-thirds of hourly workers lack emergency savings.
4 Employee Cohorts That Have Difficulty Saving
To go a step further, we’ll zoom in on four segments of the workforce that are really struggling to save:
- Workers in high deductible healthcare plans
- Workers who have student loan repayments
- Workers with rental costs greater than 30% of income
- Workers with accelerating caregiver costs
Workers Enrolled in High Deductible Healthcare Plans
As healthcare costs have risen, more workers have opted for high-deductible plans to afford the premiums. The percentage of single-coverage workers with a deductible of $2,000 or more has risen from 9% to 34% over the last decade and a half. Deductibles are much higher for family plans.
HR and benefits leaders have responded by rolling out health savings accounts. Unfortunately, few workers are funding an HSA. According to an older study, most people with an HSA have not funded it in the last 12 months.12 And one-third of HDHP enrollees do not even have an HSA. This means any unexpected healthcare expense could create a major financial shock.
Workers with Student Loan Repayments Restarting
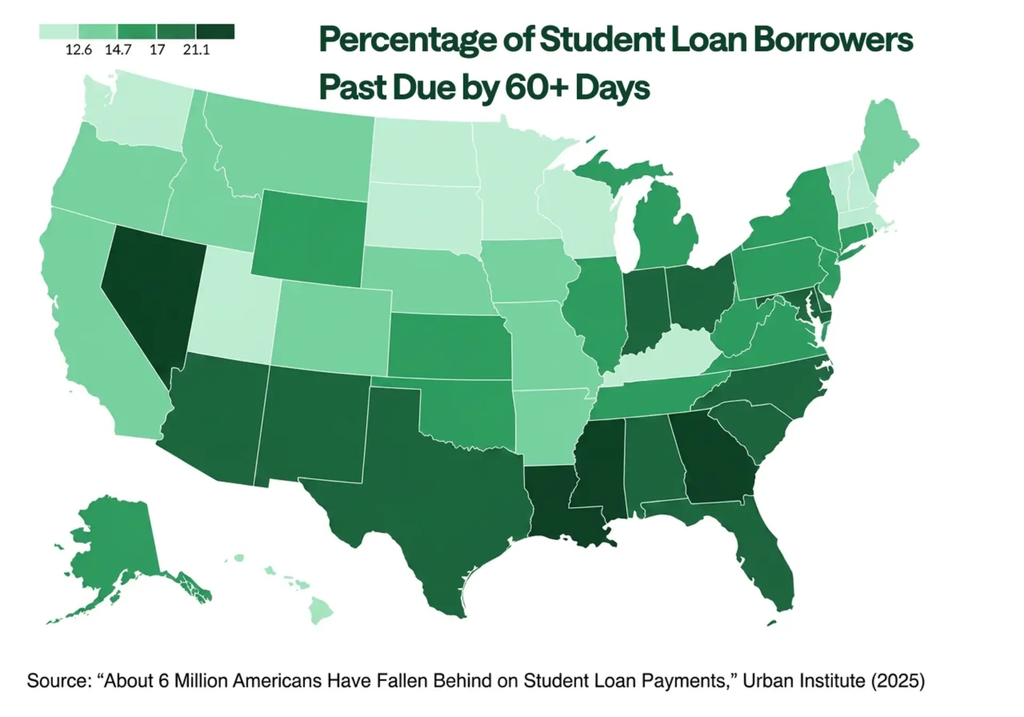
The second cohort to watch: workers with student loans. 43 million Americans owe $1.6 trillion in student loan debt. From 2020 until last year, the Department of Education did not enforce collections on any defaulted loans. That five-year pause is now over.
About 25 million borrowers have to currently make payments. Of those, 24%, or about 1 in 4, are delinquent.14 The average credit-score decline for defaulted borrowers is 91 points. A lower credit score doesn’t just affect your eligibility for mortgages, auto loans, and the like; it can also affect your ability to rent an apartment, get a mobile phone plan, or even turn on the power and water.
Workers Whose Rent Is Outpacing Income
The third cohort is a sizable one: renters. One-third of households are renters, and an increasing share are finding it harder to save. The 30% rule says you should not spend more than 30% of your income on rent. The share of Americans spending more than 30% has doubled from 24% to 49%, according to a conservative estimate by Harvard University. An alarming 1 in 4 renters spend more than half their income on rent, making it incredibly difficult to save.
Workers with Rising Childcare Costs
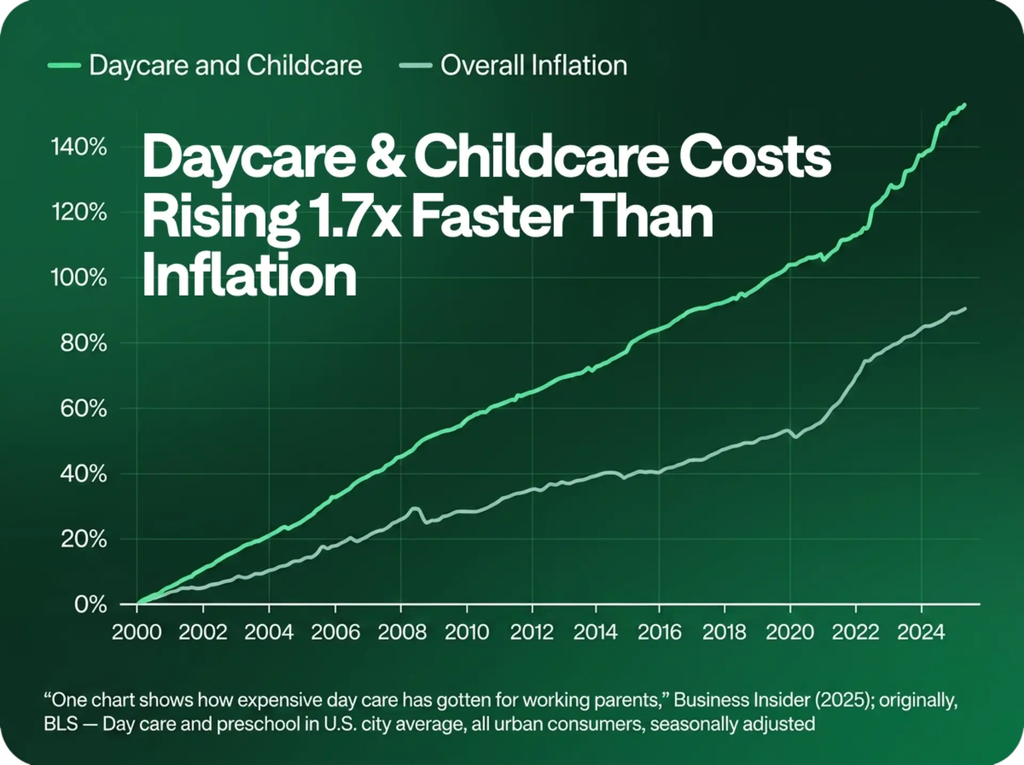
27 million Americans rely on childcare so they can go to work. Unfortunately, its cost has been rising about 1.7 times as much as that of overall inflation, which is high enough already. In some places, childcare costs more than the average rent.
How Workers Without Savings Are Coping
Workers without savings typically respond to unexpected expenses:
- They may simply not pay their bills. According to the Federal Reserve, 40% of student loan defaulters are behind on their credit card payments; 21% are late on their mortgage, and 57% are past due on auto payments.
- They can borrow. Depending on their credit profile, workers may be able to access a personal line of credit. Alarmingly, 1 in 8 workers asks a colleague or supervisor for a loan.
- They can turn to earned wage access, also known as EWA. The average worker runs out of funds 12 days after getting paid. Employers first started offering EWA a decade ago as a safer alternative to payday loans. But recent advancements in EWA technology mean it can be offered as part of a holistic financial wellness platform at no cost to either the employer or employee.
- They may be motivated to begin saving. Growing savings for unexpected expenses is a top priority for employees.
Modern EWA Can Help Workers Build Savings
These last two uses — EWA use and building savings — are connected. For context, legacy EWA programs often prioritize easy liquidity over employees’ financial progress. These apps make their money, for the most part, when workers take instant transfers. The fees add up quickly and can average $370 per year.
Modern EWA is different. It is embedded in a financial wellness platform with tools like high-yield savings, credit building, financial education, budgeting, and behavioral nudges. EWA then becomes the on-ramp for savings. Workers may enroll in the platform for early pay access. They can then transition to saving through a combination of features such as incentives, built-in nudges, and personalized goal-setting.
That’s why success is measured not by how much workers use the EWA feature to access their pay earlier, but by whether (and to what degree) they are building savings. That’s the first meaningful step toward breaking the paycheck-to-paycheck cycle.
Employers Are Offering Chime Workplace to Power Employee Savings
First Student, the country’s largest student-transportation provider, recently launched Chime Workplace and is already seeing positive results. 46% of active enrolled employees began saving within two months of launch. Of those employees, 76% continued building their savings—an early indication of the kind of financial progress employers are looking for.
Interested in offering a financial wellness platform that promotes employee saving? Request a free demo with Chime Workplace.